 Legal
AI for Law Firm Collections: Clio vs LawPay vs Custom
The job nobody owns: turning billed hours into deposited money
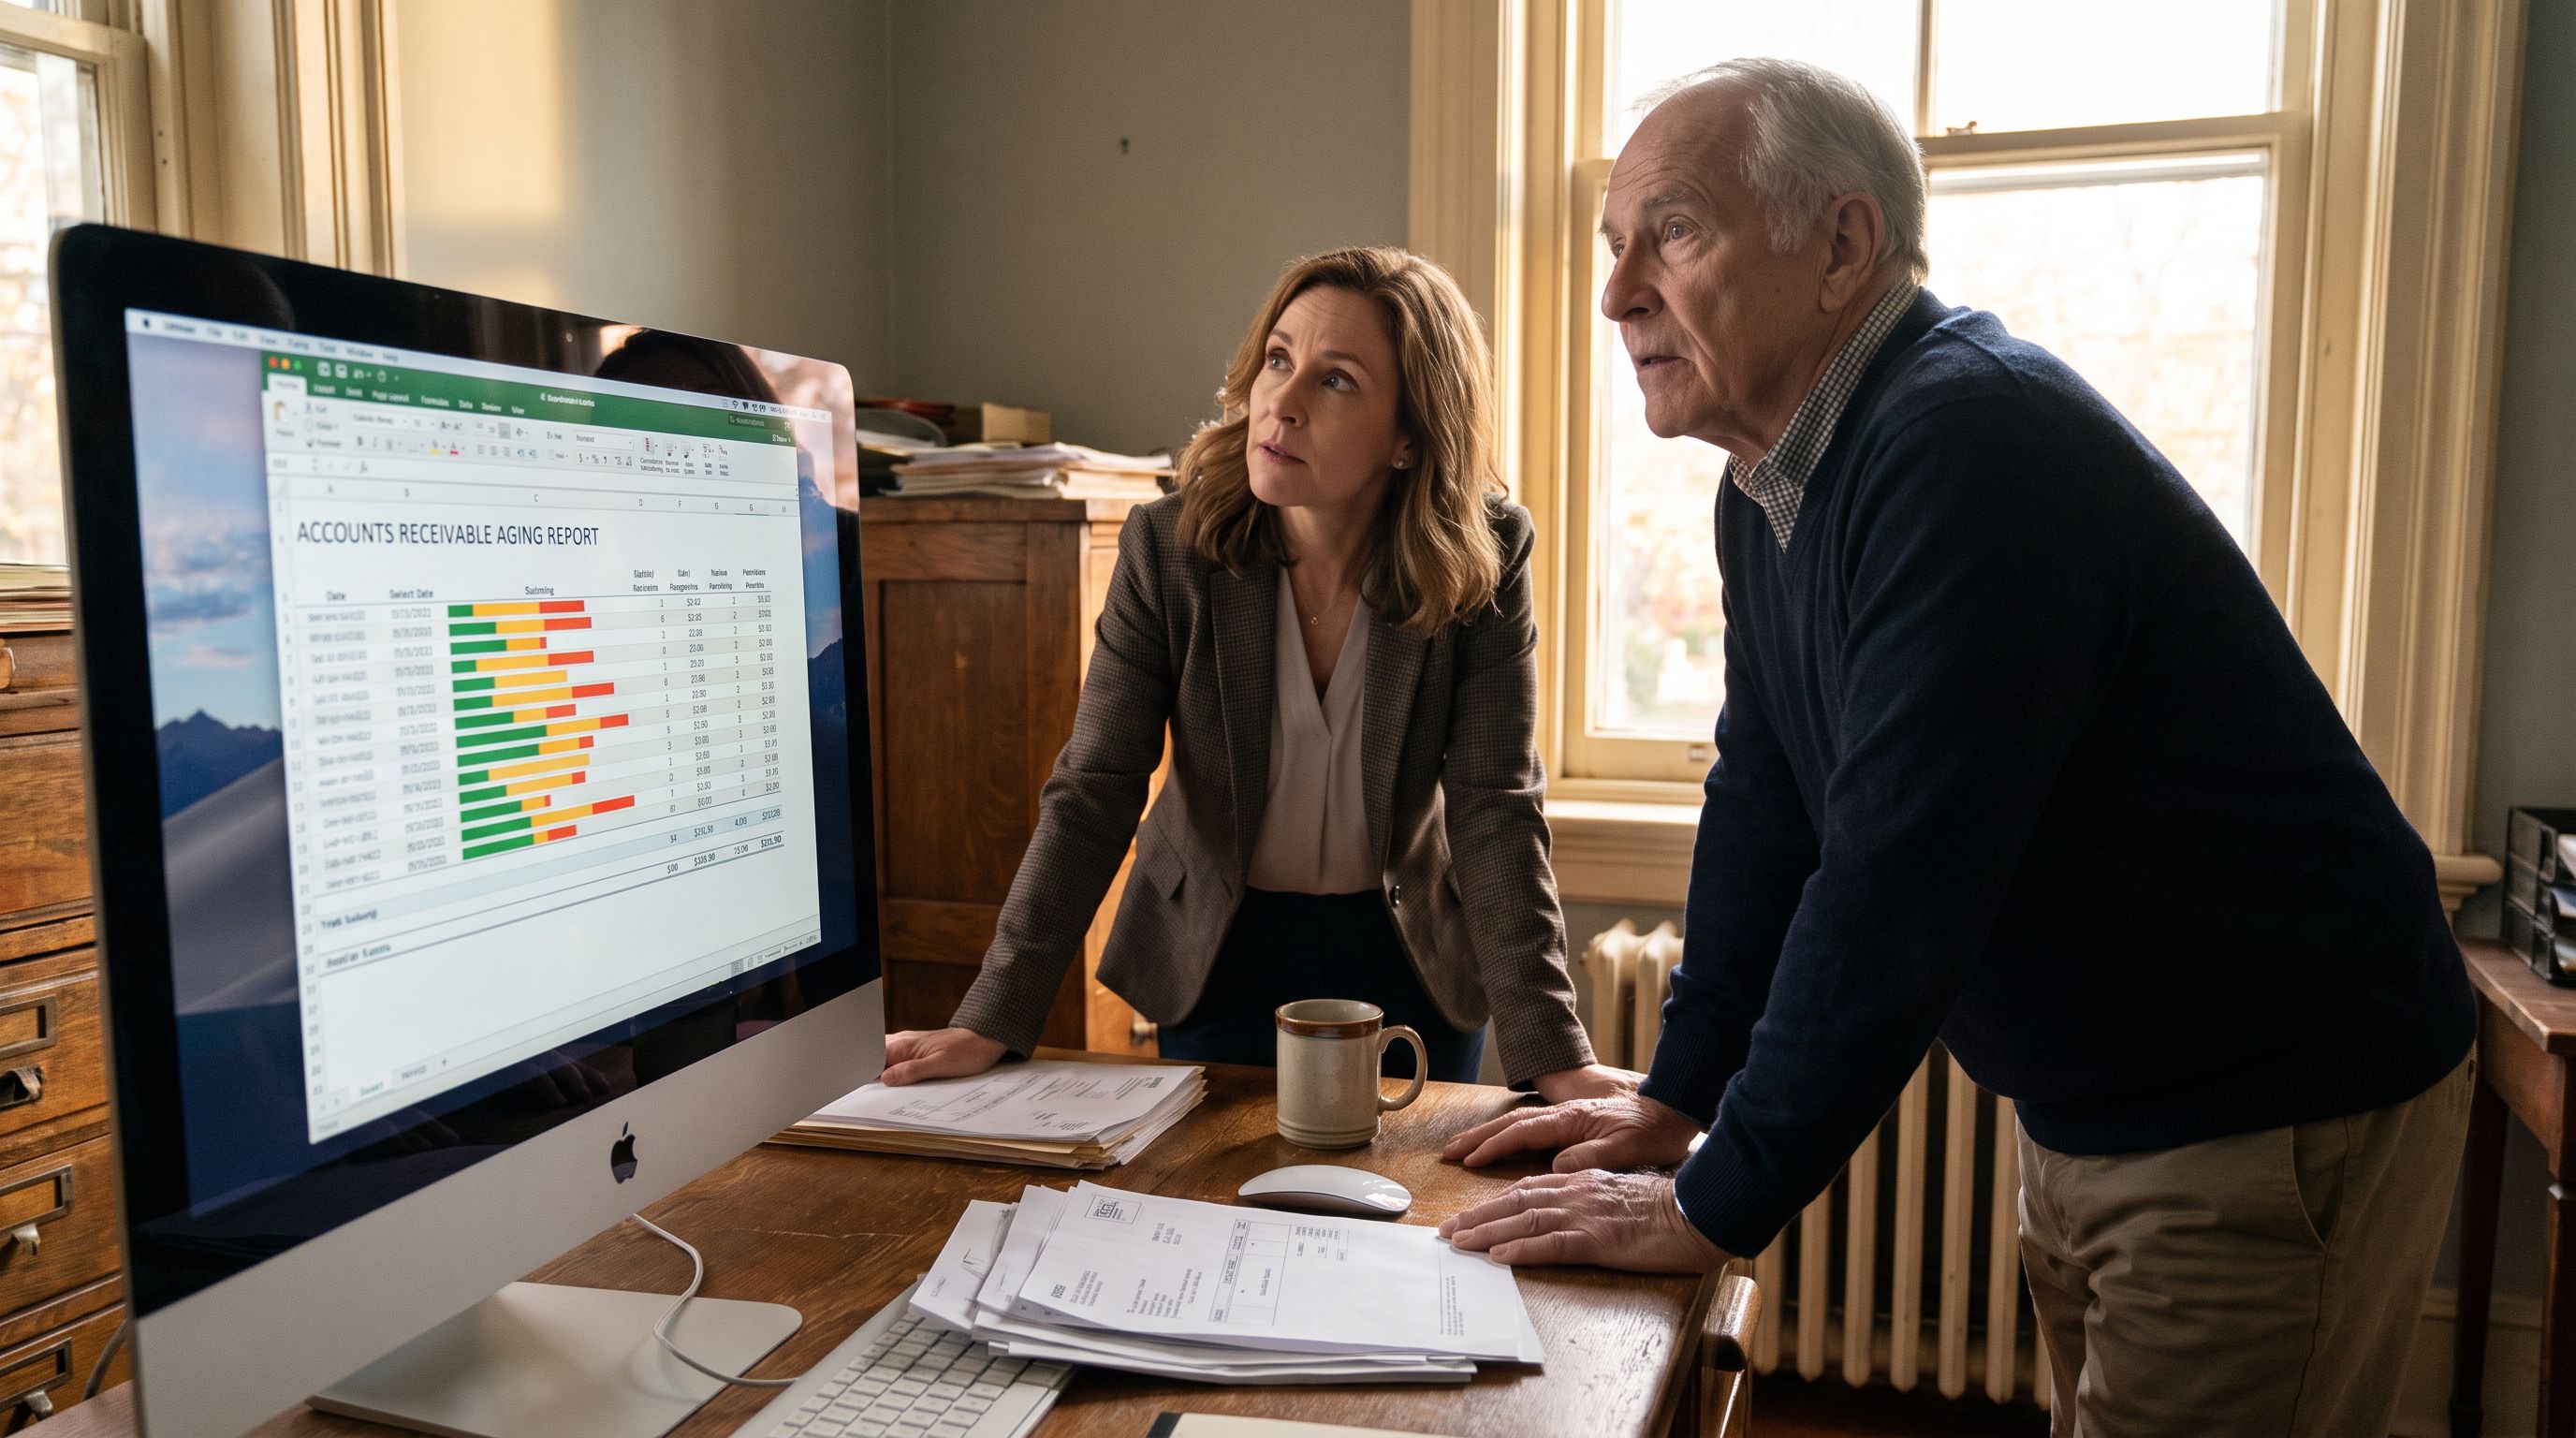
Every small firm has a version of this conversation at month end. The partner asks why cash is tight. The administrator pulls the aging report. Say it shows $140,000 in 60-plus-day buckets, half of it from three clients, and nobody has called any of them since the invoices went out. Those figures are a composite illustration, not data — swap in your own aging report as you read.
Collections is distinct from billing. Capturing time and getting invoices out is one problem. Getting invoices paid, replenishing evergreen retainers, offering payment plans before a client goes quiet, and deciding what to write off is another — different tooling, thinner margin for error.
Collections is the rare AI use case where the output is money you already earned. You’re not creating revenue — you’re stopping a leak.
Why realization and collection decide what a lawyer takes home
Firm income is arithmetic, and two of the four variables are collections variables:
Run your own figures: billable hours last year × standard rate × realization (what you billed versus what you worked) × collection (what you collected versus what you billed), minus overhead, divided by the people sharing profit. In our view, firms chasing a bigger personal income number often find the leak in the last two multipliers rather than the first two — raising rates while collecting well under your billed amount is pushing on a rope.
That is also the honest ROI model for collections automation. Don’t ask how many hours it saves. Ask: if this moves our collection rate on 60–90 day AR by two points, what are two points of our AR worth? If the answer is a rounding error, send three emails yourself. Our automation ROI walkthrough has the fuller version.
The small slice of your AR that causes most of the pain
The familiar concentration heuristic — a minority of clients produce most of the revenue — applies to receivables too. Our working assumption, offered as opinion rather than measurement: a handful of accounts hold most of your aged balance, and they are almost never fixed by another automated reminder. They’re fixed by a phone call, a payment plan, a scope conversation, or a decision to stop working.
That split determines tooling. The long tail of small, forgettable balances is an automation problem. The short head is a judgment problem. Any vendor pitching one solution for both is selling you something.
Start with the reminders already in your practice-management system
Clio, MyCase, Smokeball, PracticePanther and peers ship some combination of scheduled invoice reminders, payment links, stored cards, and payment plans. Feature sets and tiers change constantly — check vendor documentation, not any blog post including this one, for what’s included as of 2026.
They are rules-based, cheap, auditable, and handle the long tail unattended. What they don’t know: that the matter just settled, that a courtesy discount was promised, that the balance includes a disputed expert invoice, or that the client has trust funds that could be applied. That tone-deafness is the ceiling.
Fix the payment experience before you buy intelligence
LawPay and similar legal-payments providers — plus the general-business layer of QuickBooks, lockbox, and card-on-file — attack friction. If clients intend to pay but the process annoys them, this is likely your highest-return fix, and it has nothing to do with AI. Three concrete levers:
- Card-on-file authorization at engagement. Collect written payment authorization when the fee agreement is signed, not when the invoice ages. Wait, and you’re negotiating permission with someone already unhappy.
- Route by fee economics. Cards typically price as a percentage; ACH often prices as a flat per-transaction fee, so on a large balance the difference is real money. Offer both, default large balances to ACH, and confirm exact pricing with your processor.
- Evergreen replenishment triggers. Set a trust floor per matter and fire a replenishment request automatically when the balance crosses it — before work stops.
Trust and operating separation is regulated, not merely operational. ABA Model Rule 1.15 governs safekeeping client property, and every state has its own version plus rules on how processing fees interact with trust deposits. Confirm your setup against your state bar’s trust accounting rules and ethics guidance — and see our take on AI and trust accounting.
The vendor-native AI option you should price first
Practice-management and payments vendors are shipping their own AI features, including billing-narrative drafting and collections assistance. If your vendor’s version closes the context gap — the AI sees matters, trust balances, and payment history because it lives inside the system of record — that is usually the cheaper path: no integration surface, no maintenance, bundled into a subscription. Prefer it when your AR sits in one system, your workflows are standard, and you can test output on real accounts. Be skeptical when the feature is announced but unreleased, priced at an uncertain tier, or blind to data outside that vendor’s walls.
When a custom collections agent is worth scoping
An AI agent is a model given tools and a goal, running a loop: pull data, reason, act, check. For collections, you connect an assistant like Claude to your billing system through MCP — the Model Context Protocol, an open standard for granting AI governed, permissioned access to specific data and actions rather than a blanket login. You then define a skill: packaged instructions so every account is handled the way your firm would handle it.
-
Pull and segment
Read AR by client, matter, responsible attorney, and age bucket; pull trust balances and payment history. -
Classify
Forgotten, partial-payer, retainer below threshold, disputed, gone quiet, write-off candidate — using your rules, not the model’s instincts. -
Draft
Different outreach per class, referencing the matter, last payment, trust balance, proposed plan. Drafts, not sends. -
Escalate
Anything over a dollar threshold, disputed, or touching withdrawal goes to a named person with file context. -
Close the loop
After approval: send, log to the matter, set follow-up, report what changed since last week.
Cost side, as planning assumptions rather than a quote: assume one billing system with a documented API, read-mostly access, a single named owner for the skill file, and weekly human review. Scope is typically a discovery pass, a build, and a supervised pilot where every draft is read — plan in weeks, not days. The recurring cost is what firms forget: someone works the queue weekly and edits the skill file whenever fee terms, classification rules, or the billing schema change. Get fixed-scope quotes from two builders and compare against the vendor-native option’s annual price.
Where this breaks
The agent can misread a credit memo and tell a paid-up client they owe money — a relationship error no efficiency gain offsets. It can’t hear that a client’s business is failing. It will confidently propose a payment plan your fee agreement doesn’t permit. And an agent drafting into a queue nobody reviews produces zero dollars.
Our recommended sequence: turn on built-in reminders, fix payment friction, assign a human owner to AR for ninety days, price your vendor’s native AI, then ask whether a custom agent solves a problem you still have. Our own observation, not an aggregate finding: the usual failure isn’t bad AI — it’s buying intelligence on top of a process nobody owned. Same pattern as vendor agents versus custom builds.
Where is your firm losing billable hours?
Get a free automation audit: we map your intake-to-invoice workflow and show you exactly what's worth automating — before you spend a dollar.
Get a free automation auditRelated guides
AI Matter Closeout: Clio vs NetDocuments vs Custom Agent
Matter closeout and file retention automation compared: practice-management built-ins, DMS governance, and a custom AI agent — plus what must stay human.
Read guide →
OCR for Law Firms: Acrobat vs ABBYY vs a Custom Agent
OCR for law firms compared: Adobe Acrobat, ABBYY, cloud OCR APIs, and a custom AI filing agent that classifies, extracts, and files scanned PDFs.
Read guide →
Family Law Financial Disclosure: AI Tools vs Custom Agent
Compare family law software, general AI assistants, and a custom AI agent for financial disclosure abstraction — what each does well, and where AI breaks.
Read guide →